
Quick answer: a renters policy typically has three parts: personal property coverage for your belongings, liability coverage if someone is hurt or you damage someone else’s property, and additional living expenses if a covered loss makes your home unlivable. Flood and earthquake damage are usually excluded unless you buy separate coverage.
A landlord’s insurance protects the building. It does not usually pay to replace a tenant’s couch, laptop or winter coat after a fire. That gap is the reason renters insurance exists, and it explains why so many leases ask for proof of coverage. People often put off buying a policy because they assume their stuff is not worth much. A quick tally of everything inside a typical apartment tends to change that view.
This guide covers what a standard renters policy usually includes, what it often leaves out, how limits and deductibles shape a payout, and what to think about with roommates, pets and valuables. The descriptions draw on consumer education from the Insurance Information Institute (III) and the National Association of Insurance Commissioners (NAIC). Policies differ by company and state, so your own policy language is the final authority. The content is general information only and does not constitute advice about any specific policy.
The Three Core Parts of a Renters Policy
Most renters policies are built on a standard form that has three major coverages. Understanding each makes it easier to read a quote.
Personal property
Personal property coverage pays when covered perils damage or destroy your belongings. Furniture, clothing, electronics, kitchenware and similar items typically fall under it. The III notes that this coverage generally applies to your belongings at home and often elsewhere, such as items stolen from a car or a hotel room, subject to policy terms.
Policies list the perils they cover. Common named perils include fire, smoke, lightning, windstorm, theft, vandalism and certain kinds of water damage, such as a burst pipe. Some policies cover “all risks” except for what they exclude, which usually offers broader protection.
How a payout is calculated depends on the valuation method, covered in the next section.
Personal liability
Liability coverage responds when you are legally responsible for injuring someone or damaging their property. A guest who slips on a wet kitchen floor and needs medical care is a typical example. Another is a kitchen fire that spreads and damages the neighboring unit. Liability coverage can help pay legal defense costs and settlements or judgments, up to the policy limit.
A related feature, medical payments to others, can cover small medical bills for a guest hurt at your home regardless of fault. It usually has a much lower limit than liability.
Standard liability coverage does not generally apply to your own injuries, to intentional acts or to business activity. Someone running a business from home often needs additional coverage.
Additional living expenses
If a covered event makes your home unlivable, loss of use coverage, also called additional living expenses (ALE), can help pay for the extra costs of living elsewhere while repairs are made. The III describes this as covering items such as hotel bills, restaurant meals beyond your normal food costs and similar expenses. Time and dollar limits apply, and the event must be a covered peril.
Actual Cash Value Versus Replacement Cost
When property is damaged, an insurer pays based on one of two valuation methods. The choice shows up on the policy, and it can change the payout a great deal.
- Actual cash value (ACV) pays the replacement cost minus depreciation. A five-year-old television is worth less than a new one, so the payout reflects the age and condition of the item.
- Replacement cost pays what it would cost to replace the item with a comparable new one, generally without subtracting depreciation. Many policies pay part of the amount up front and the remainder after you actually replace the item.
Replacement cost coverage typically costs more in premium, but it can make a major difference after a large loss. The article on insurance that provides replacement value looks at that topic in more detail.
Limits, Sublimits and Deductibles
A policy has an overall limit for personal property, which you choose when buying. That number should reflect the real cost of replacing your belongings, not a guess.
Within the overall limit, many policies set lower sublimits for certain categories. The III points out that items such as jewelry, watches, furs, firearms, silverware, cash and collectibles often have special caps, sometimes much lower than people expect. If you own valuables that exceed those caps, a scheduled personal property endorsement, sometimes called a rider or floater, can cover specific items at a stated value.
Deductibles work as they do for other insurance: the amount you pay before the insurer pays. Choosing a higher deductible usually lowers the premium, but it also means a larger out-of-pocket cost at the time of a claim. Some policies use separate deductibles for certain perils.
The premium itself depends on factors such as location, coverage amounts, deductible, the building’s features and claims history. For a general look at those drivers, see the piece on what determines an insurance premium. Online calculators can give a rough estimate, but only an actual quote reflects your address and details.
Comparing quotes sensibly
Two quotes with the same price can protect very differently. Line them up on the same terms before choosing.
- Check whether personal property is valued at actual cash value or replacement cost.
- Compare the liability limit and the medical payments limit.
- Note the deductible and whether it differs for wind, hail or other perils.
- Look for limits on loss of use, including any day or dollar cap.
- Ask about sublimits for jewelry, electronics and similar categories.
- Find out whether sewer backup, identity theft restoration or equipment breakdown can be added.
Bundling renters coverage with an auto policy from the same insurer sometimes lowers the combined price, though it is worth confirming whether the discount applies in your state. Paying annually instead of monthly can also reduce fees at some companies. Discounts for safety devices such as smoke detectors or deadbolts exist at some insurers, so ask what is available.
Common Exclusions to Know About
Every policy has exclusions. Several are especially important for renters.
- Flood. Standard renters policies generally exclude flood damage, including rising water from storms and overflowing rivers. Flood coverage is sold separately through the National Flood Insurance Program (NFIP) and private insurers, and renters can buy contents coverage for their belongings. FEMA’s FloodSmart.gov offers details.
- Earthquake. Damage from earth movement is typically excluded and available through an endorsement or separate policy.
- Sewer or drain backup. This often needs an add-on.
- Pests and wear and tear. Maintenance issues and infestations are generally not covered.
- Intentional damage. Damage you cause on purpose is excluded.
- Roommates’ belongings. Unless a roommate is named on your policy, their property generally is not covered.
- Business property. Inventory and equipment used for a business may be limited or excluded.
Exclusions work the same way in other lines of insurance. Our guide to types of auto insurance coverage shows how car policies list what they cover and what they leave out. Renters policies follow the same pattern, so read the exclusions section before you need it.
Roommates, Pets and Guests
Several household situations come up repeatedly.
Roommates. A renters policy covers the people named on it, and often relatives who live with them. Unrelated roommates typically need their own policies, or must be added as named insureds. Some landlords require every adult tenant to carry coverage. Whether adding a roommate is cheaper than separate policies depends on the insurer.
Pets. Liability coverage may help if your dog bites a visitor, but some insurers exclude certain breeds or limit coverage for dog-related claims. Disclose pets when you apply and ask the insurer how they are treated. Your pet’s own medical care is not covered under a standard renters policy.
Guests. Liability coverage often applies to guests injured at your home. Damage that guests do to your belongings is treated like any other covered peril, depending on how it happened.
Landlord requirements. Some leases ask for liability coverage at a specified amount and for the landlord to be listed as an interested party or additional interest. The article on whether renters insurance is mandatory explains when it is required, and a piece on obtaining a renters insurance declaration page shows what proof of coverage generally looks like.
Building a Home Inventory
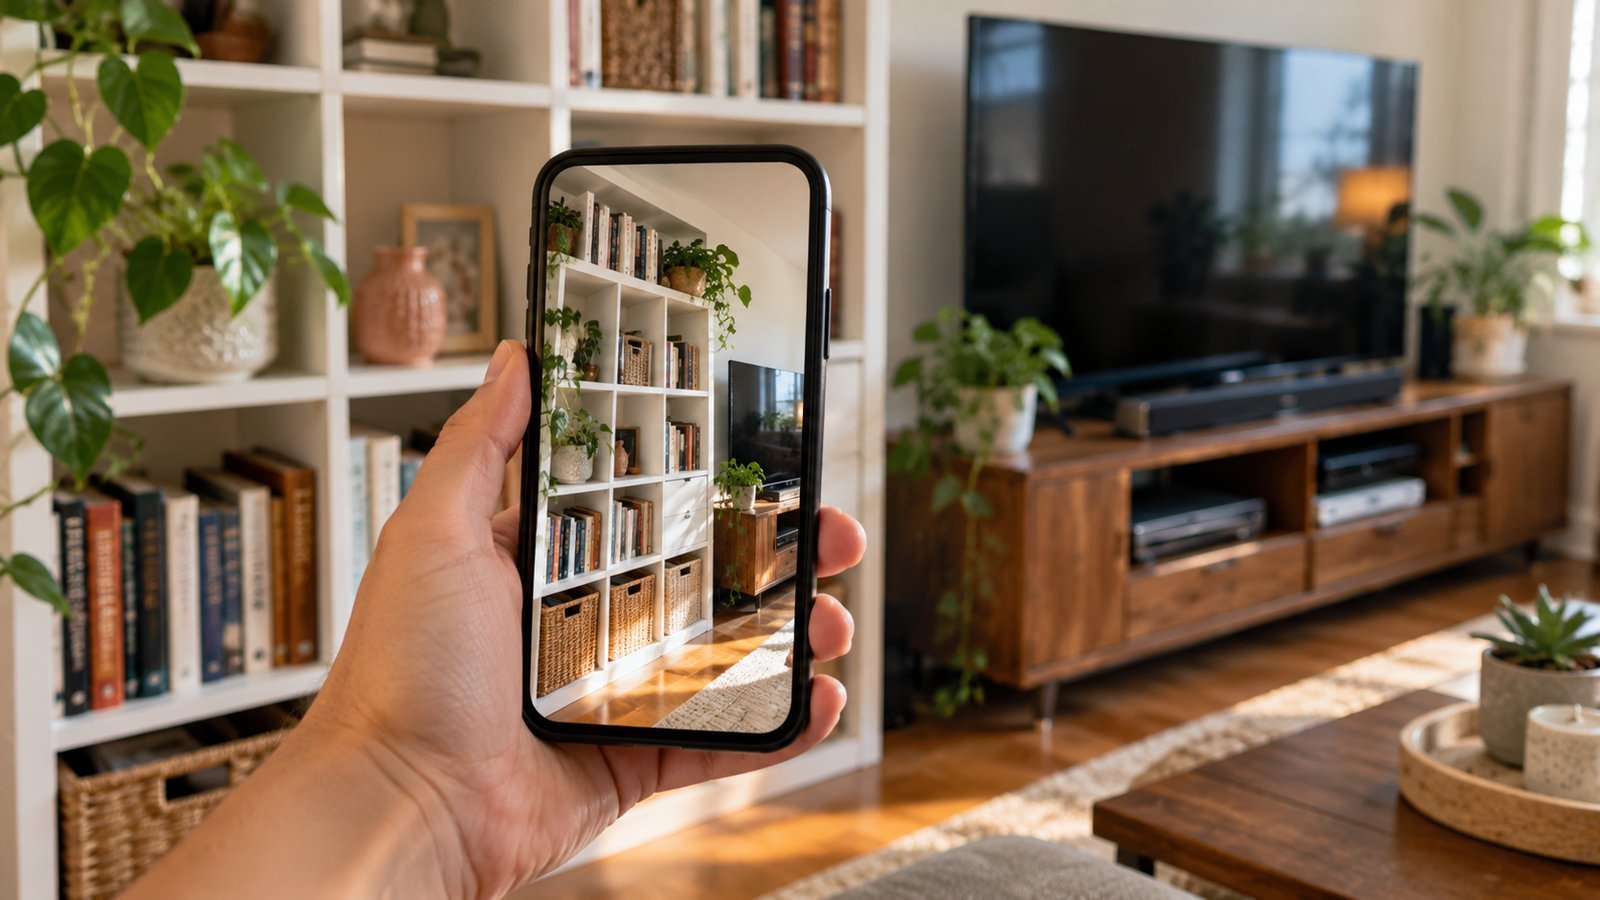
A home inventory makes claims easier and helps you pick a sensible coverage limit. The NAIC offers a free home inventory app and encourages consumers to keep records. A simple approach works fine.
- Walk through each room with a phone and record a video, opening drawers and closets and speaking the descriptions aloud.
- Take photos of valuable items and any serial numbers.
- Save receipts, appraisals and warranty papers in a folder.
- Estimate the replacement cost of each item or category.
- Save the files somewhere other than your home, such as cloud storage, so they survive a fire.
- Update the inventory after major purchases and once a year.
Totaling those figures often shows people that their belongings are worth more than they guessed. Clothing, kitchen items, electronics and furniture add up quickly, even in a small apartment.
Filing a Claim in General Terms
If a covered loss occurs, the usual steps are fairly consistent. Make sure everyone is safe, then contact the police for theft or vandalism and get a report number. Prevent further damage when it is reasonable and safe to do so, and keep receipts for temporary repairs and lodging. Contact the insurer promptly, share your inventory and photos, and keep a record of every conversation. The adjuster reviews the claim and the insurer decides, within policy terms, what is covered. If you disagree with a decision, you can ask for a written explanation and contact your state department of insurance.
Situations that surprise renters
A few real-life details are worth a look before they matter. Moving to a new apartment usually means updating the policy address, and a policy generally does not follow you automatically without notice. Property in a storage unit may be covered only up to a reduced limit, so ask your insurer how stored belongings are treated. Short stays, such as a student living in a dorm, may fall under a parent’s policy in some cases, though dorm coverage depends on the policy and the school. Lastly, canceling mid-term can produce a prorated refund at many insurers, and the explainer on prorated insurance describes how that math works in general terms. Reading renewal notices each year helps you catch changes in price and coverage. Keep the policy number, the insurer’s claims phone line and your agent’s contact details somewhere you can reach from a phone, since a fire or flood may leave you without your paperwork.
This article is general information only. It is not insurance, legal or financial advice, and it does not describe any specific policy. Check your policy documents, ask your insurer or agent about your situation, and contact your state department of insurance with regulatory questions.
Frequently Asked Questions
Does renters insurance cover my roommate's belongings?
Usually not, unless the roommate is named on your policy. Many insurers recommend that each unrelated roommate have a separate policy.
Does renters insurance cover flood damage?
Standard policies generally exclude flood. Separate flood coverage is available through the NFIP and private insurers, and renters can insure their contents.
Will my landlord's insurance replace my belongings?
Generally not. A landlord’s policy typically protects the building and the landlord’s liability, not a tenant’s personal property.
Is theft covered away from home?
Often yes, subject to policy terms and limits. Property stolen from a car or while traveling is commonly covered, though some items have special limits.
How much coverage do I need?
That depends on the replacement cost of your belongings and the liability risk you face. A home inventory is a practical starting point, and an agent can discuss limits.